Factoring Misconceptions
Factoring has critics. This post answers the common objections to factoring and shows where it helps a business with slow-paying…
Waiting 30, 60 or 90 days for customers to pay strains payroll and inventory purchases. Invoice factoring turns unpaid invoices into working capital without adding a loan to your balance sheet.
Cash flow is one of the biggest challenges growing businesses face. Even profitable companies can struggle to cover payroll, purchase inventory, or accept new projects when customers take 30, 60, or 90 days to pay their invoices. Instead of waiting for payments to arrive, invoice factoring provides immediate access to working capital by advancing cash against your outstanding receivables.
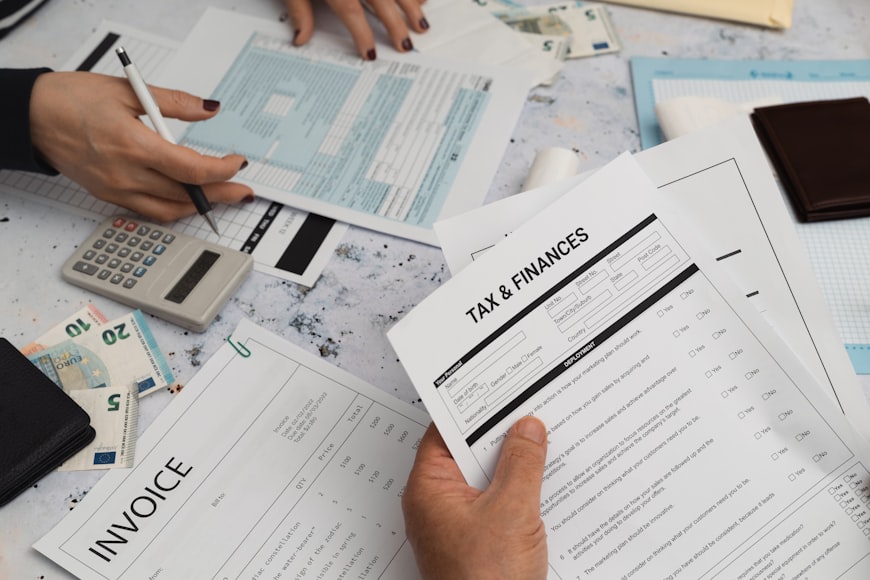
Unlike a traditional bank loan, invoice factoring isn’t based primarily on your business’s credit history or profitability. Instead, funding is secured by your unpaid invoices, allowing businesses to unlock cash that is already tied up in accounts receivable. This makes factoring an effective solution for companies experiencing rapid growth, seasonal demand, or extended customer payment terms.
One of the greatest advantages of invoice factoring is flexibility. As your sales increase, your available funding can grow as well because financing is directly linked to the value of your invoices. Rather than being limited by a fixed line of credit, businesses can access additional working capital as they generate more receivables.
The funds received through factoring can be used for virtually any business expense, including payroll, inventory purchases, equipment, marketing, fuel costs, supplier payments, or taking on larger customer contracts. Having predictable cash flow allows business owners to focus on growth instead of worrying about delayed payments.
For many businesses, factoring also simplifies accounts receivable management. Depending on the program, the factoring company may assist with invoice collections and payment processing, reducing administrative work while maintaining professional communication with your customers.
Industries such as staffing, transportation, manufacturing, wholesale distribution, construction, and professional services commonly use invoice factoring because they frequently operate with long payment cycles while needing immediate cash to support daily operations.
If your business has strong customers but experiences slow invoice payments, invoice factoring can provide a practical alternative to traditional financing. By turning outstanding invoices into working capital, you gain the financial flexibility to invest in growth, meet operational expenses, and confidently pursue new opportunities without taking on additional debt.
Whether you’re looking to bridge temporary cash flow gaps or build a long-term funding strategy, invoice factoring offers a fast, flexible, and scalable financing solution that grows alongside your business.
Common Questions
Most businesses receive 80–90% of the invoice value up front. Freight carriers receive a full advance, which is standard in freight factoring, and we make exceptions to the range case by case. When your customer pays, we release the remaining balance to you, minus our fee.
Setting up your account typically takes 24–48 hours from signup. After that, we fund invoices the same day you submit them.
Sigma factors with recourse, so an invoice your customer never pays comes back to you. You can add credit insurance, which pays when an insured customer fails to pay, under the policy's terms. We don't offer non-recourse factoring. It costs more and covers only a customer's bankruptcy or insolvency, so late payment and non-payment stay with you anyway. Compare the options.
Yes. A Notice of Assignment tells your customer to send payment to Sigma, so how we handle collections and communication matters. The staffing and service business pages explain how that works in practice.
Factoring is the sale of invoices you've already issued, so the funding grows with your sales. A line of credit is a loan with its own underwriting and covenants. Read factoring vs. a line of credit for a side-by-side comparison.
Tell us about your business and the invoices you want funded. Within 48 hours you get a proposal with your advance rate, fee and terms, and you don't have to sign it.
Your advance
Get Your Proposal